Understanding Aged Receivables: Your Business Health Guide
Aged receivables are unpaid customer invoices categorized by the length of time they have remained outstanding, typically organized into 30-day increments or "buckets." These figures represent capital owed to your business that is currently unavailable, serving as a critical diagnostic tool for assessing liquidity and credit risk.
Why are aged receivables critical for your cash flow?
For any business operating in South Africa today, cash flow is the lifeblood of sustainability. Aged receivables represent more than just numbers on a balance sheet; they reflect the efficiency of your sales-to-cash cycle. When a significant portion of your revenue is tied up in long-term outstanding invoices, your ability to meet operational expenses, such as payroll, rent, and inventory replenishment, is severely compromised. High levels of aged receivables often signal that a company is effectively acting as an interest-free lender to its clients, which is an unsustainable model for growth.
Monitoring these figures allows finance teams and entrepreneurs to identify potential bad debts before they become write-offs. The longer an invoice remains unpaid, the lower the probability of full recovery. By maintaining a sharp focus on the age of your receivables, you can transition from a reactive stance—chasing money when the bank account is empty—to a proactive strategy that ensures consistent liquidity. This foresight is what separates thriving enterprises from those struggling to survive market fluctuations. Understanding these metrics is the first step toward reclaiming control over your financial destiny.
At 6ELA , we understand that managing these numbers can be overwhelming for busy professionals. That is why our platform serves as your Business Debt Co-Pilot, automating the oversight of these critical figures. By integrating AI-driven insights, we help you see the stories behind the numbers, allowing you to prioritize collections based on risk and value rather than just date.
How do you read an aged receivables report?
An aged receivables report, often called an accounts receivable (AR) aging report, is a standard accounting document that lists all unpaid customer invoices. The report is structured in columns, each representing a specific time frame from the invoice due date. Understanding how to interpret these "buckets" is essential for diagnosing the health of your credit control processes.
Typically, the report includes the following categories:
- Current (0-30 Days): Invoices that are within their standard payment terms. These are generally considered healthy and expected to be paid soon.
- 31-60 Days: These accounts are slightly overdue. They require immediate attention and a gentle reminder to ensure they don't slip further.
- 61-90 Days: These represent a significant risk. At this stage, standard reminders should escalate to formal follow-ups or direct communication.
- 91+ Days: Accounts in this bracket are at high risk of becoming bad debt. They often require specialized recovery efforts or legal escalation.
- Total Outstanding: The sum of all unpaid invoices across all buckets, providing a snapshot of your total exposure.
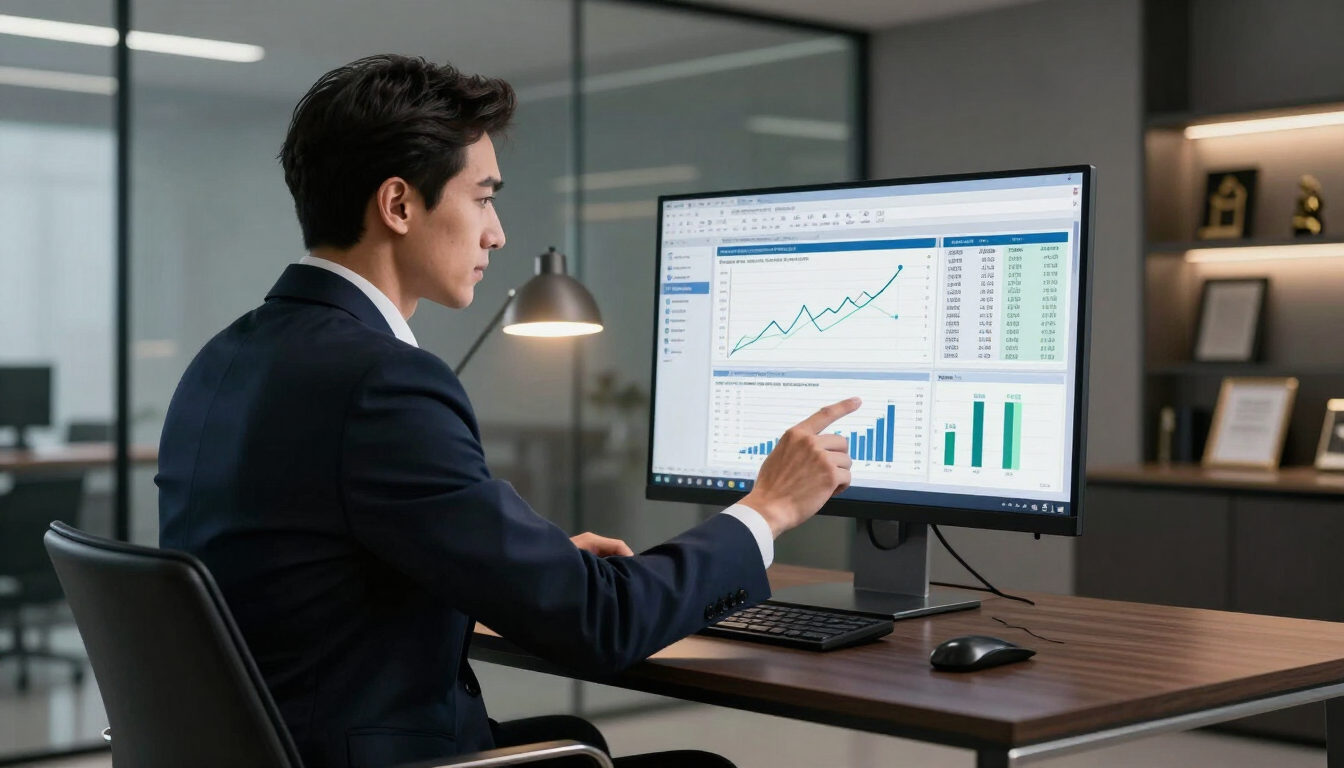
Reading the report involves looking for trends. For instance, if you notice a growing percentage of debt shifting from the 31-60 day bucket into the 61-90 day bucket, it indicates a breakdown in your collection process or a systematic issue with your client base. Conversely, a report where the majority of receivables stay in the "Current" bucket suggests a robust and efficient credit management system.
Key metrics to track in your aging report
While the aging report itself provides a wealth of information, there are specific metrics you should calculate to gain a deeper understanding of your business health. These KPIs (Key Performance Indicators) allow you to benchmark your performance over time and against industry standards. Tracking these helps in making informed decisions about credit limits and customer relationships.
One of the most important metrics is the Days Sales Outstanding (DSO) . This calculates the average number of days it takes for your company to collect payment after a sale has been made. A high DSO relative to your payment terms indicates that your customers are taking too long to pay, which can lead to cash flow bottlenecks. Another vital metric is the Collection Effectiveness Index (CEI) , which measures your team's ability to collect funds from customers during a specific period. A CEI close to 100% signifies an extremely efficient collection process.
Furthermore, you should monitor the Percentage of AR Over 90 Days . If this percentage is creeping up, it is a clear red flag that your debt recovery efforts need reinforcement. By focusing on these metrics, you can identify which clients are chronic late payers and adjust your credit terms accordingly. This data-driven approach ensures that you are not just selling, but selling profitably and sustainably. You can find more resources on these metrics in our blog section .
What are the main causes of delinquent accounts?
Understanding why aged receivables accumulate is the first step toward preventing them. In many cases, the cause is not simply a "bad" customer, but rather a friction point in the administrative or communication process. By identifying these root causes, businesses can implement targeted solutions that address the problem at its source rather than just treating the symptom of late payment.
Common causes include:
- Inaccurate Invoicing: Errors in pricing, quantities, or contact information can give customers a valid reason to delay payment until the issue is resolved.
- Disorganized Follow-ups: Without a consistent schedule for reminders, customers may deprioritize your invoice in favor of more persistent creditors.
- Poor Credit Vetting: Onboarding customers without properly assessing their creditworthiness often leads to a high volume of delinquent accounts.
- Disputes Over Goods or Services: If a customer is unhappy with the delivery, they may withhold payment as a negotiation tactic.
- Client Financial Distress: In a volatile economy, some clients may simply lack the liquidity to pay their bills on time.
Addressing these issues requires a multifaceted approach. Streamlining your internal billing processes is essential, as is maintaining clear and open lines of communication with your clients. When you understand the "why" behind the delay, you can apply the right level of pressure—or offer the right level of support—to secure the payment.
The hidden costs of uncollected business debt
The impact of aged receivables goes far beyond a temporary dip in bank balances. There are several hidden costs associated with uncollected debt that can erode your profit margins and hinder your ability to compete in the market. One of the primary costs is the opportunity cost of capital . Every Rand tied up in an overdue invoice is a Rand that cannot be reinvested into marketing, new equipment, or research and development.
Additionally, there is the administrative cost of collections . The time your finance team or sales staff spends chasing late payments is time stolen from more productive activities. Then there is the cost of bad debt write-offs . When an account becomes truly uncollectible, you lose not only the profit margin but also the cost of the goods or services already provided. Finally, high aged receivables can damage your credit rating and borrowing power , making it more difficult and expensive to secure financing when you need it most. Recognizing these costs underscores the importance of an automated, efficient recovery system like 6ELA.
How can AI-driven tools accelerate debt recovery?
In the modern business environment, manual follow-ups are no longer sufficient. The volume of data and the speed of commerce require a more sophisticated approach. This is where Artificial Intelligence (AI) and automation come into play. AI-driven tools can analyze historical payment patterns to predict which customers are likely to pay late, allowing you to intervene before the invoice even becomes overdue. This predictive capability is a game-changer for credit control.
Automated platforms can handle the repetitive task of sending reminders across multiple channels—email, SMS, and WhatsApp—ensuring that your brand stays top-of-mind for the debtor. Unlike human collectors, AI doesn't get tired, forgetful, or uncomfortable during difficult conversations. It applies a consistent, professional persistence that has been proven to accelerate recovery times significantly. Furthermore, AI can help segment your aged receivables, identifying which accounts should be handled with a soft touch and which require immediate legal escalation.
By leveraging the 6ELA ecosystem , businesses can transform their recovery process from a manual chore into a streamlined, high-tech operation. Our platform doesn't just send messages; it provides actionable intelligence that helps you understand the health of your entire receivables portfolio in real-time. This level of clarity empowers you to make strategic decisions that protect your cash flow and support long-term business health.
Proven strategies to optimize your credit control
Optimizing your credit control requires a balance of clear policies, effective communication, and the right technology. Start by establishing a formal credit policy that outlines your payment terms, late fees, and the steps you will take if a payment is missed. Ensure that every new customer signs this policy as part of their onboarding process. This sets expectations from day one and provides you with a solid foundation for collection efforts.
To improve your results, consider these strategies:
- Offer Multiple Payment Options: Make it as easy as possible for customers to pay you by offering credit card, EFT, and mobile payment links.
- Send Pre-Due Reminders: A friendly reminder three days before an invoice is due can prevent many accounts from ever entering the "31-60 day" bucket.
- Incentivize Early Payment: Small discounts for payments made within 10 days can significantly improve your DSO.
- Escalate Promptly: Don't wait until 90 days to take action; have a clear escalation path that includes phone calls and formal demands.
- Use Data to Refine Terms: Regularly review your aging report to identify chronic late payers and move them to shorter terms or cash-on-delivery.
Summary: Protecting Your Business Health
Understanding aged receivables is vital for maintaining a healthy, liquid business. These numbers provide a clear map of where your revenue is trapped and which areas of your credit control need immediate improvement. By tracking key metrics like DSO and utilizing an aging report, you can identify risks early and take proactive steps to ensure your cash flow remains robust. The hidden costs of uncollected debt—ranging from administrative drain to lost opportunity—make efficient recovery a top priority for every finance professional and entrepreneur.
To summarize, take these next steps:
- Review your aging report weekly to identify trends in delinquency.
- Calculate your Days Sales Outstanding (DSO) to benchmark your efficiency.
- Implement AI-driven automation via 6ELA to handle reminders and escalations.
- Refine your credit policies to minimize future exposure to bad debt.
If you are ready to transform your debt collection process and reclaim your time, contact our team today to learn how 6ELA can serve as your Business Debt Co-Pilot. Consistent cash flow isn't just a goal; it's the foundation of your future success.
Recent Posts